
RIA Ideas - All That Glitters
Buffered Growth Note · Worst-of GLD / GDX
Gold stopped tracking stocks, 20% below its high, with the Street calling for new highs.
Gold’s correlation to the S&P 500 fell to roughly zero in late August after running above 0.8 in June (Bloomberg via Vol Pulse, 9/6/2026). In the same stretch, Goldman Sachs Research put a $4,900/oz year-end target on gold, up from about $4,300 on 9/10/2026.
Both gold (GLD, -20.5%) and the gold miners (GDX, -18.7%) sit about a fifth below their highs while the S&P 500 is 2.6% from its record (Yahoo Finance, 9/15/2026). An asset that has stopped moving with stocks, with a bullish Street call and a 20% pullback already behind it, may be worth a look as a hedge with a cushion. The note below keys off the worse of the two, with the first 20% of any decline absorbed.
Gold and stocks stopped moving together
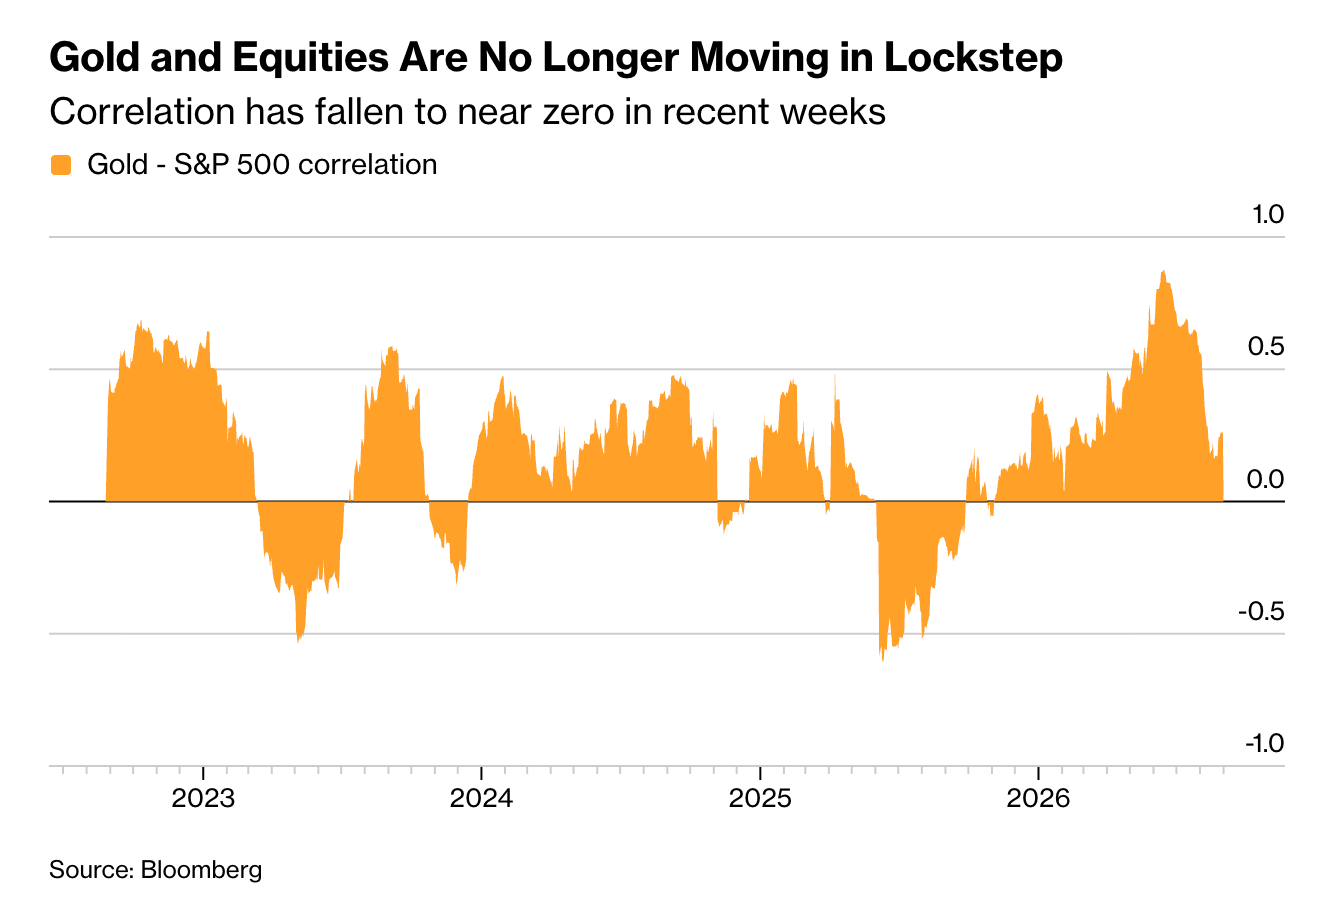
Chart: Bloomberg, via Volatility Pulse 9/6/2026 · marinelayeradvisors.com/insights
Here is an example, indicative pricing from multiple issuers on 9/16/26 (terms may change with market conditions):
3-Year Buffered Growth Note
Worst-of GLD / GDX · Indicative pricing from multiple issuers
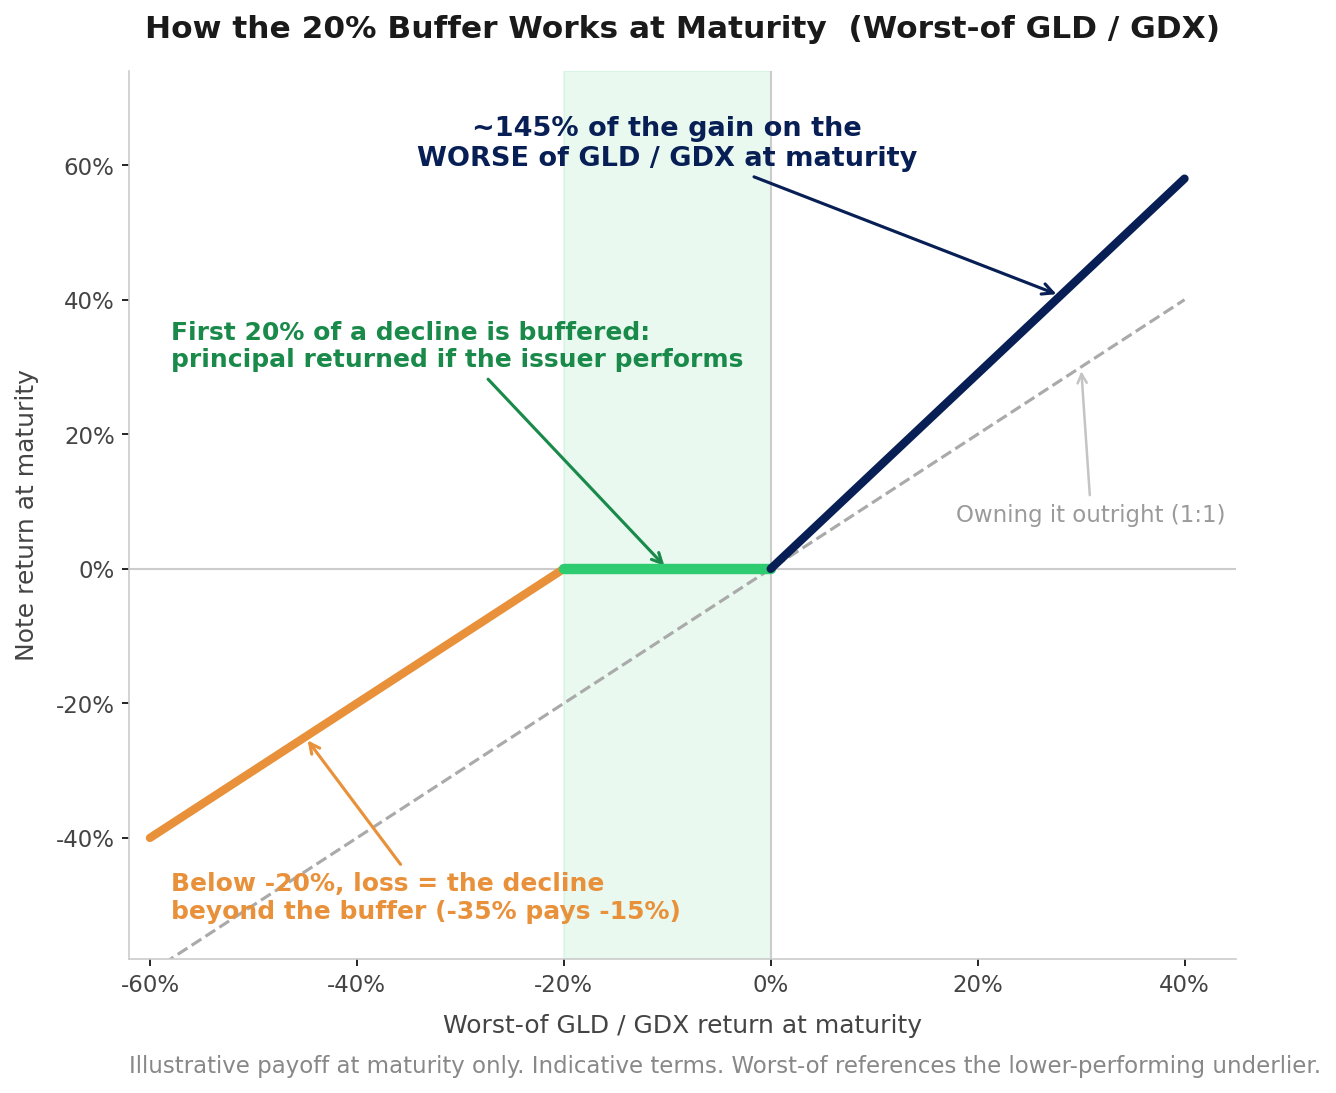
Upside participation | ~145% of any gain in the worse performer of GLD and GDX, uncapped, measured at maturity |
Downside protection | 20% hard buffer: the first 20% of any decline in the worse performer is absorbed |
Below the buffer | 1:1 loss on the decline beyond 20% (a 35% drop in the worse performer would mean a 15% loss) |
Tenor | 3 years, point-to-point |
Principal | Principal is at risk beyond the buffer. Return of principal also depends on the issuer performing its obligations in full. Notes are unsecured senior obligations of the issuer. |
At maturity the note may pay ~145% of any gain, with no cap, in whichever of gold (GLD) or the gold miners (GDX) performed worse. If the worse performer finishes down 20% or less, principal may be returned in full. Beyond that, losses run 1:1 past the buffer. Other pairings may be available, subject to issuer availability at the time of pricing.
These were indicative levels from multiple issuers, priced on 9/16/26. Pricing can vary depending on market conditions.
Here is how the note may pay at maturity:
Want to see more thematic trades for your customers?
Any investment decision must be based solely on the issuer’s prospectus and pricing supplement, which are available on request.
This material is intended solely for the recipient and may not be forwarded, reproduced or distributed to retail investors.
This material is for informational purposes only and does not constitute a recommendation or an offer to buy or sell any security. Data sourced from Yahoo Finance as of 9/15/2026, Bloomberg via Volatility Pulse as of 9/6/2026 and Goldman Sachs Research as of 9/11/2026, and has not been independently verified. The correlation chart is Bloomberg’s calculation, reproduced as published, and correlation can change quickly. The Goldman Sachs forecast is that firm’s view, not ours, and is not a guarantee of any outcome. All note terms shown are indicative levels obtained from multiple issuers on 9/16/26, are marked with a tilde where approximate, and are subject to change, final pricing, issuer availability and market conditions at the time of execution. The note references the worse-performing of GLD and GDX: the upside participation and the buffer are both measured on whichever of the two has performed worse at maturity, so a gain in one may be offset by a decline in the other. Principal is at risk: if the worse performer finishes more than 20% below its initial level at maturity, the investor may lose 1% of principal for every 1% of decline beyond the buffer. Every outcome described in this material, including the return of principal within the buffer, assumes the issuer of the note performs its obligations in full. These notes are unsecured senior obligations of the issuer and are not guaranteed, insured or collateralized. An issuer default, or a deterioration in issuer credit, could result in the loss of some or all of an investment regardless of how the underliers perform. The notes pay no interest, are not listed on any securities exchange and may have limited or no interim liquidity. Past performance is not indicative of future results. Structured notes involve risks including potential loss of principal and may not be suitable for all investors.