
RIA Ideas - Small Cap Torque
Catapult Note · IWM (Russell 2000)
The crowd betting against small caps (IWM) is at a three-year extreme, and insurance against being wrong is near its three-year low.
Short positioning in Russell 2000 futures is at its most extreme in three years, while the cost of a one-month IWM call sits near the bottom of its three-year range: maximum short, minimum insurance against being wrong (Goldman Sachs, via Volatility Pulse 10/14/2026). IWM, the Russell 2000 ETF, is up 12.8% this year against 13.7% for SPY, the S&P 500 ETF (Yahoo Finance, as of 10/20/2026).
A catapult is built for a crowded short. Here is one, indicatively priced on 10/20/2026 (terms may change with market conditions): if IWM is at or above its start at year one, the note pays a one-time ~13% call premium and ends. If not, it runs to three years and pays 150% of any gain, uncapped, with principal returned unless IWM is down more than 30%. This is different from our August small-cap piece, which was a growth note on valuation.
Maximum short, minimum insurance
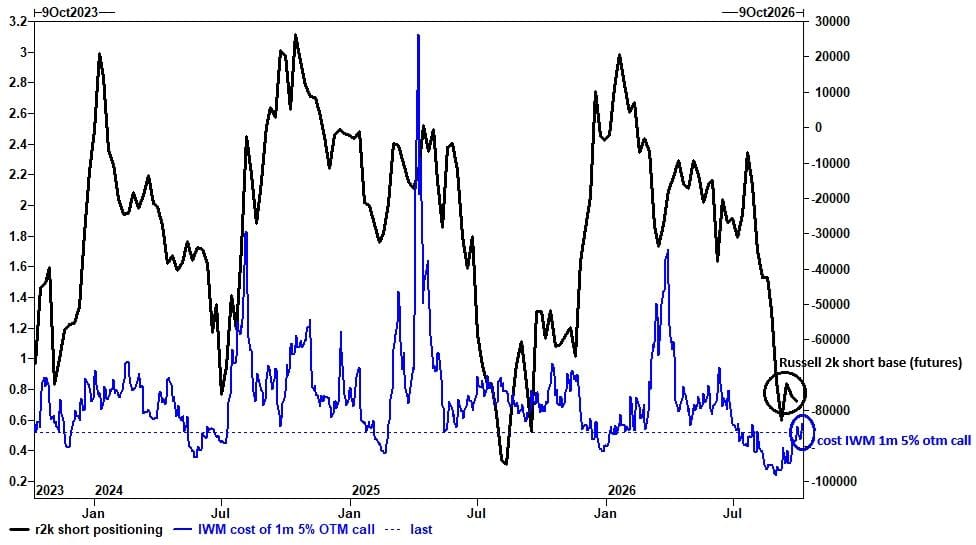
Chart: Brian Garrett, Goldman Sachs, via Zero Hedge, via Volatility Pulse 10/14/2026. · marinelayeradvisors.com/insights
Small caps have kept pace this year
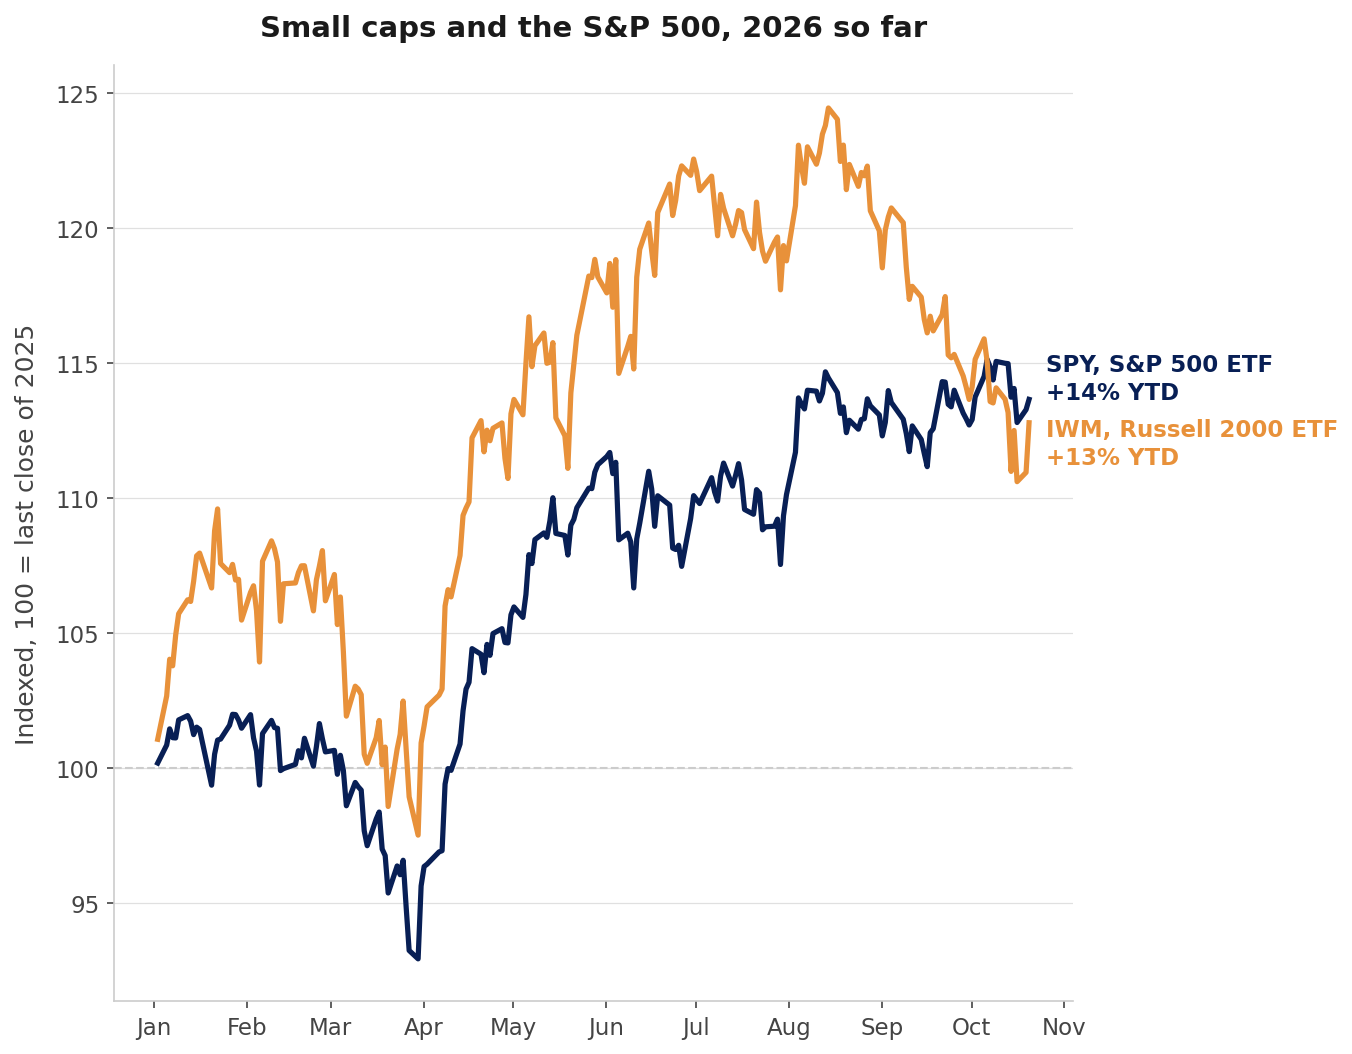
Source: Yahoo Finance, daily closes, as of 10/20/2026. Returns indexed to the last close of 2025.
The structure, indicatively priced on 10/20/2026:
3-Year Catapult Note
IWM (iShares Russell 2000 ETF) · Indicative levels
Early call | At year one, if IWM is at or above its start: a one-time ~13% call premium, and the note ends, if the issuer performs |
Upside if never called | 150% of any IWM gain, uncapped, paid at maturity (up 30% pays +45%) |
Downside at maturity | 70% barrier, observed at maturity only. Principal returned if IWM is down 30% or less; below that, the full decline from the start (down 35% pays down 35%) |
Principal | All payments on the note are obligations of the issuer and are subject to its credit risk. |
Tenor / coupons | 3 years, one call observation at year one, no coupons |
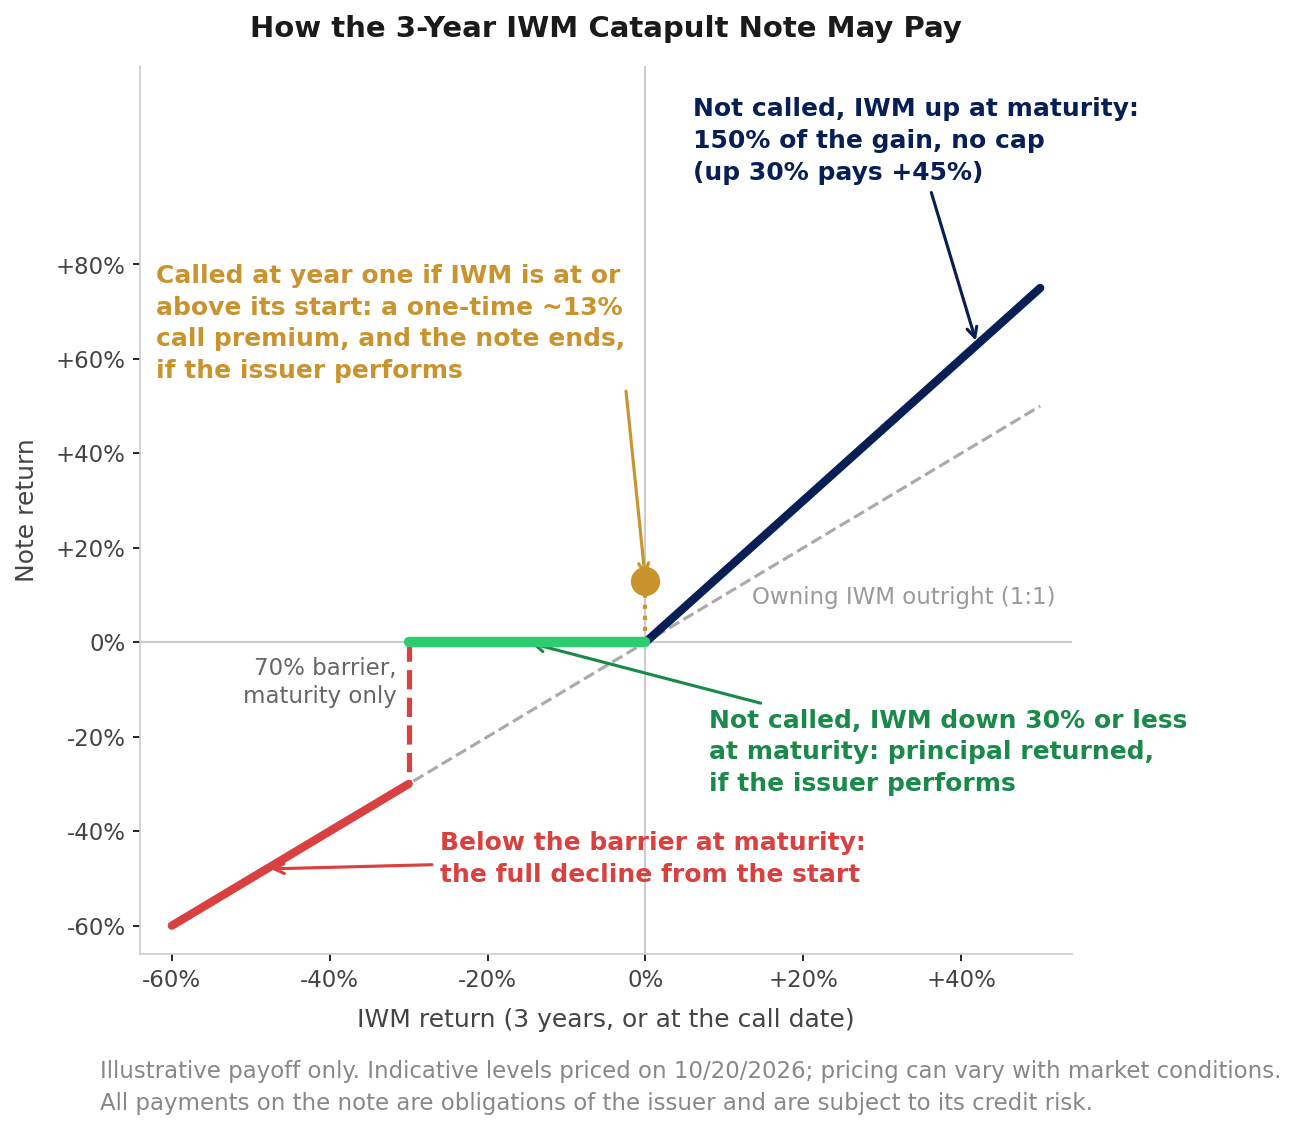
Two ways to get paid. If IWM is at or above its start at year one, the note may pay the ~13% call premium and end early, if the issuer performs; a larger year-one gain still pays only the premium. If it is not called, the note may pay 150% of any IWM gain at maturity, with no cap, and may return principal in full as long as IWM is down 30% or less; below the 70% barrier there is no cushion and the note may take IWM’s full decline from its start. If the structure appeals but the index does not, the underlier can be changed, subject to issuer availability at the time of pricing.
These were indicative levels priced on 10/20/2026. Pricing can vary depending on market conditions.
Here is how the note may pay:
Want to see more thematic trades for your customers?
Any investment decision must be based solely on the issuer’s prospectus and pricing supplement, which are available on request.
This material is intended solely for the recipient and may not be forwarded, reproduced or distributed to retail investors.
This material is for informational purposes only and does not constitute a recommendation or an offer to buy or sell any security. The positioning chart is Goldman Sachs’ as published via Zero Hedge and Volatility Pulse 10/14/2026; the return data is Yahoo Finance’s as of 10/20/2026; none of it has been independently verified. Positioning data describes the past and says nothing about future returns. All terms shown are indicative levels priced on 10/20/2026 and are subject to change, final pricing, issuer availability and market conditions at the time of execution; they do not represent an offer or a quotation. Values marked with a tilde are approximate. Return of principal depends on the issuer performing its obligations in full. The notes are unsecured senior obligations of the issuer, are not insured or collateralized, and an issuer default or credit deterioration could result in the loss of some or all of an investment regardless of how IWM performs. The 70% barrier provides contingent protection only: if IWM finishes below 70% of its initial level at maturity, the investor is exposed to the full decline of IWM from its initial level, with no cushion. If the note is called at year one, the ~13% call premium is the only return and no further payment is made, however far IWM has risen. The offering documents may call the barrier a knock-in or trigger level; their defined terms govern. The notes pay no interest, are not listed on any securities exchange and may have limited or no interim liquidity. Past performance is not indicative of future results. Structured notes involve risks including potential loss of principal and may not be suitable for all investors.